Builder Loan Credit Tightens for 19th Straight Quarter
A National Association of Home Builders survey found credit for land, development and construction loans tightened again in the third quarter, matching what banks told the Federal Reserve.
By Alex Pham · · 2 min read
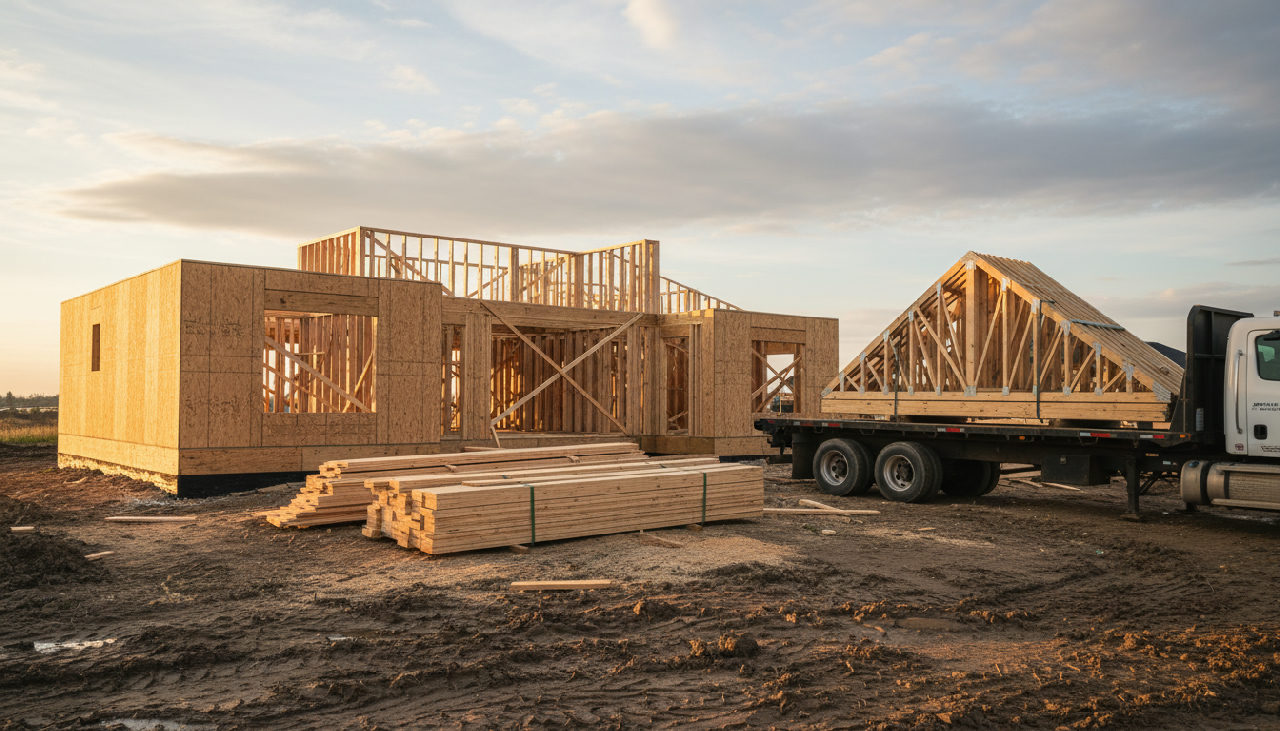
For home builders, the bank vault has been closing a little more every quarter since early 2022. Credit for residential land acquisition, development and construction tightened again in the third quarter of 2026, according to a National Association of Home Builders survey reported by HousingWire [1].
NAHB's net easing index came in at negative 15.3, meaning more builders saw tighter credit than looser credit. That makes 19 consecutive quarters of tightening, NAHB economist Paul Emrath wrote on Nov. 13 [1].
The cost of building money
- Contract rates on speculative single-family construction loans climbed to 7.72% from 7.28% in the second quarter [1].
- Pre-sold single-family construction loans rose to 7.27% from 7.01% over the same span [1].
- After counting points, the effective rate on spec loans held at 11.83%, versus 11.82% a quarter earlier [1].
- 32% of surveyed builders used construction-to-permanent loans tied to the final buyer, covering 58% of their homes on average [1].
The builders' view matches the lenders'. In the Fed's October Senior Loan Officer Opinion Survey, banks said they tightened standards for every commercial real estate category, including construction and land development loans, while demand for those loans weakened [2]. NAHB put the Fed's index for residential construction lending at negative 15.5 [1].
But lower upfront fees softened the blow. Initial points fell in all four loan categories NAHB tracks, and the effective rate on pre-sold homes actually dipped to 11.47% from 11.67% [1].
What it means for you
Higher builder financing costs eventually show up in home prices and lot supply. By our math, an all-in rate of 11.83% costs a builder about $59,150 a year on a $500,000 spec construction loan. The jump in the contract rate alone, from 7.28% to 7.72%, adds roughly $2,200 a year on that loan, by our math. Investors buying new construction should expect builders to favor pre-sold homes over spec inventory.
Zoom out
NAHB argues tight construction lending is an underrated brake on new supply, especially for entry-level homes [1]. With banks also reporting weaker demand for all residential mortgage categories, both ends of the pipeline are slowing at once [2].
This is market commentary, not investment advice.
Sources
- [1]HousingWire, Builder credit conditions tighten for 19th straight quarter, Nov 13, 2026.
- [2]Federal Reserve Board, The October 2026 Senior Loan Officer Opinion Survey on Bank Lending Practices, Nov 2, 2026.